Landlord Insurance
Landlord insurance is a category of specialist insurance designed for people who let residential property, covering risks that standard home insurance excludes by design. A standard home policy is written on the assumption that the policyholder occupies the property; once tenants move in, that assumption breaks down, and most policies either exclude the rental scenario or become voidable for non-disclosure under the Insurance Act 2015. Landlord insurance fills that gap with cover structured around the specific risks of letting: structural damage, third-party liability, loss of rental income, and, optionally, legal costs and tenant default.
A buy-to-let mortgage lender will almost always require buildings insurance as a condition of the loan, making it functionally mandatory even though no statute compels it.
Do I need landlord insurance, and is it a legal requirement?
No UK law requires a private landlord to hold landlord insurance as such, but three practical constraints make it close to unavoidable. First, buy-to-let mortgage terms almost universally require adequate buildings insurance, and letting without it breaches the loan agreement. Second, under the Employers' Liability (Compulsory Insurance) Act 1969, a landlord who employs anyone in connection with the property, such as a cleaner or on-site manager, must hold employers' liability cover with at least £5 million of indemnity. Third, an uninsured landlord is personally exposed to property damage, liability awards, and income loss that can individually run to tens of thousands of pounds. Landlords letting without a mortgage can lawfully go uninsured; very few sensibly do.
What does landlord insurance cover?
Buildings insurance is the foundation of most policies, protecting the structure and permanent fixtures against defined perils including fire, flood, storm, escape of water, subsidence, and malicious damage. The sum insured should reflect the rebuild cost, not the market value. For leasehold flats, buildings insurance is typically the freeholder's responsibility, so leaseholders should check the headlease before buying their own policy.
Property owners' liability covers legal costs and compensation if a tenant, visitor, or contractor is injured on the property and holds the landlord responsible. Claims can reach six figures in serious cases, and the cover usually extends to communal areas, external paths, and shared stairways.
Loss of rent cover pays the rental income the landlord cannot recover while the property is uninhabitable after an insured event such as fire or flood. It does not pay out if the tenant simply stops paying; that is a different product entirely.
Optional add-ons
Landlord contents insurance covers the landlord's own furniture, appliances, and fittings. It never covers the tenant's belongings, which need the tenant's own contents policy.
Accidental damage extends cover to unintentional damage, such as a tenant breaking a window, beyond the standard named perils.
Legal expenses insurance covers possession proceedings, eviction, and certain tenancy disputes, commonly up to a stated limit of around £50,000. This cover has become more relevant since the abolition of Section 21, as every possession claim now requires a court process.
Rent guarantee insurance, also called tenant default insurance, pays out when a tenant stops paying rent regardless of the property's condition, and usually bundles legal expenses for repossession. It has strict eligibility conditions: tenant referencing must have been completed before the tenancy, and most policies require an assured periodic tenancy. Some insurers also offer a squatters insurance extension for vacant properties, covering eviction costs and damage by unauthorised occupants.
How much does landlord insurance cost?
Basic buildings-only cover starts from roughly £170 a year, with typical combined policies averaging around £220 to £230 annually for a property with a £200,000 rebuild value, before add-ons. Premiums rise with rebuild cost, claims history, tenancy type, and property construction; HMOs and holiday lets sit in higher-risk categories with their own pricing. From working with self-managing landlords across the UK, the most common gap we encounter is the absent legal expenses extension: it typically adds £50 to £100 a year to the premium, and landlords who have faced an undefended possession claim or a boundary dispute invariably wish they had taken it.
What landlord insurance does not cover
Standard policies typically exclude general wear and tear, mechanical or electrical breakdown not caused by an insured event, unoccupied property beyond a defined period (commonly 30 to 60 days) without an endorsement, deliberate damage by the landlord, and losses arising from a failure to comply with statutory obligations, such as letting a property that fails MEES standards. The tenant's own possessions are never covered.
The Insurance Act 2015 and disclosure
Under the Insurance Act 2015, landlords must make a fair presentation of the risk when taking out or renewing a policy. Failing to disclose material facts can result in a claim being declined or the policy avoided. Facts landlords most often under-declare include multiple sharers (which may reclassify the property as an HMO), short-term or holiday letting, periods of unoccupancy, and prior claims or subsidence history. Insurers may also ask about the tenancy type and letting arrangement; answer whatever is asked accurately, because an innocent omission can still defeat a claim.
Tax treatment
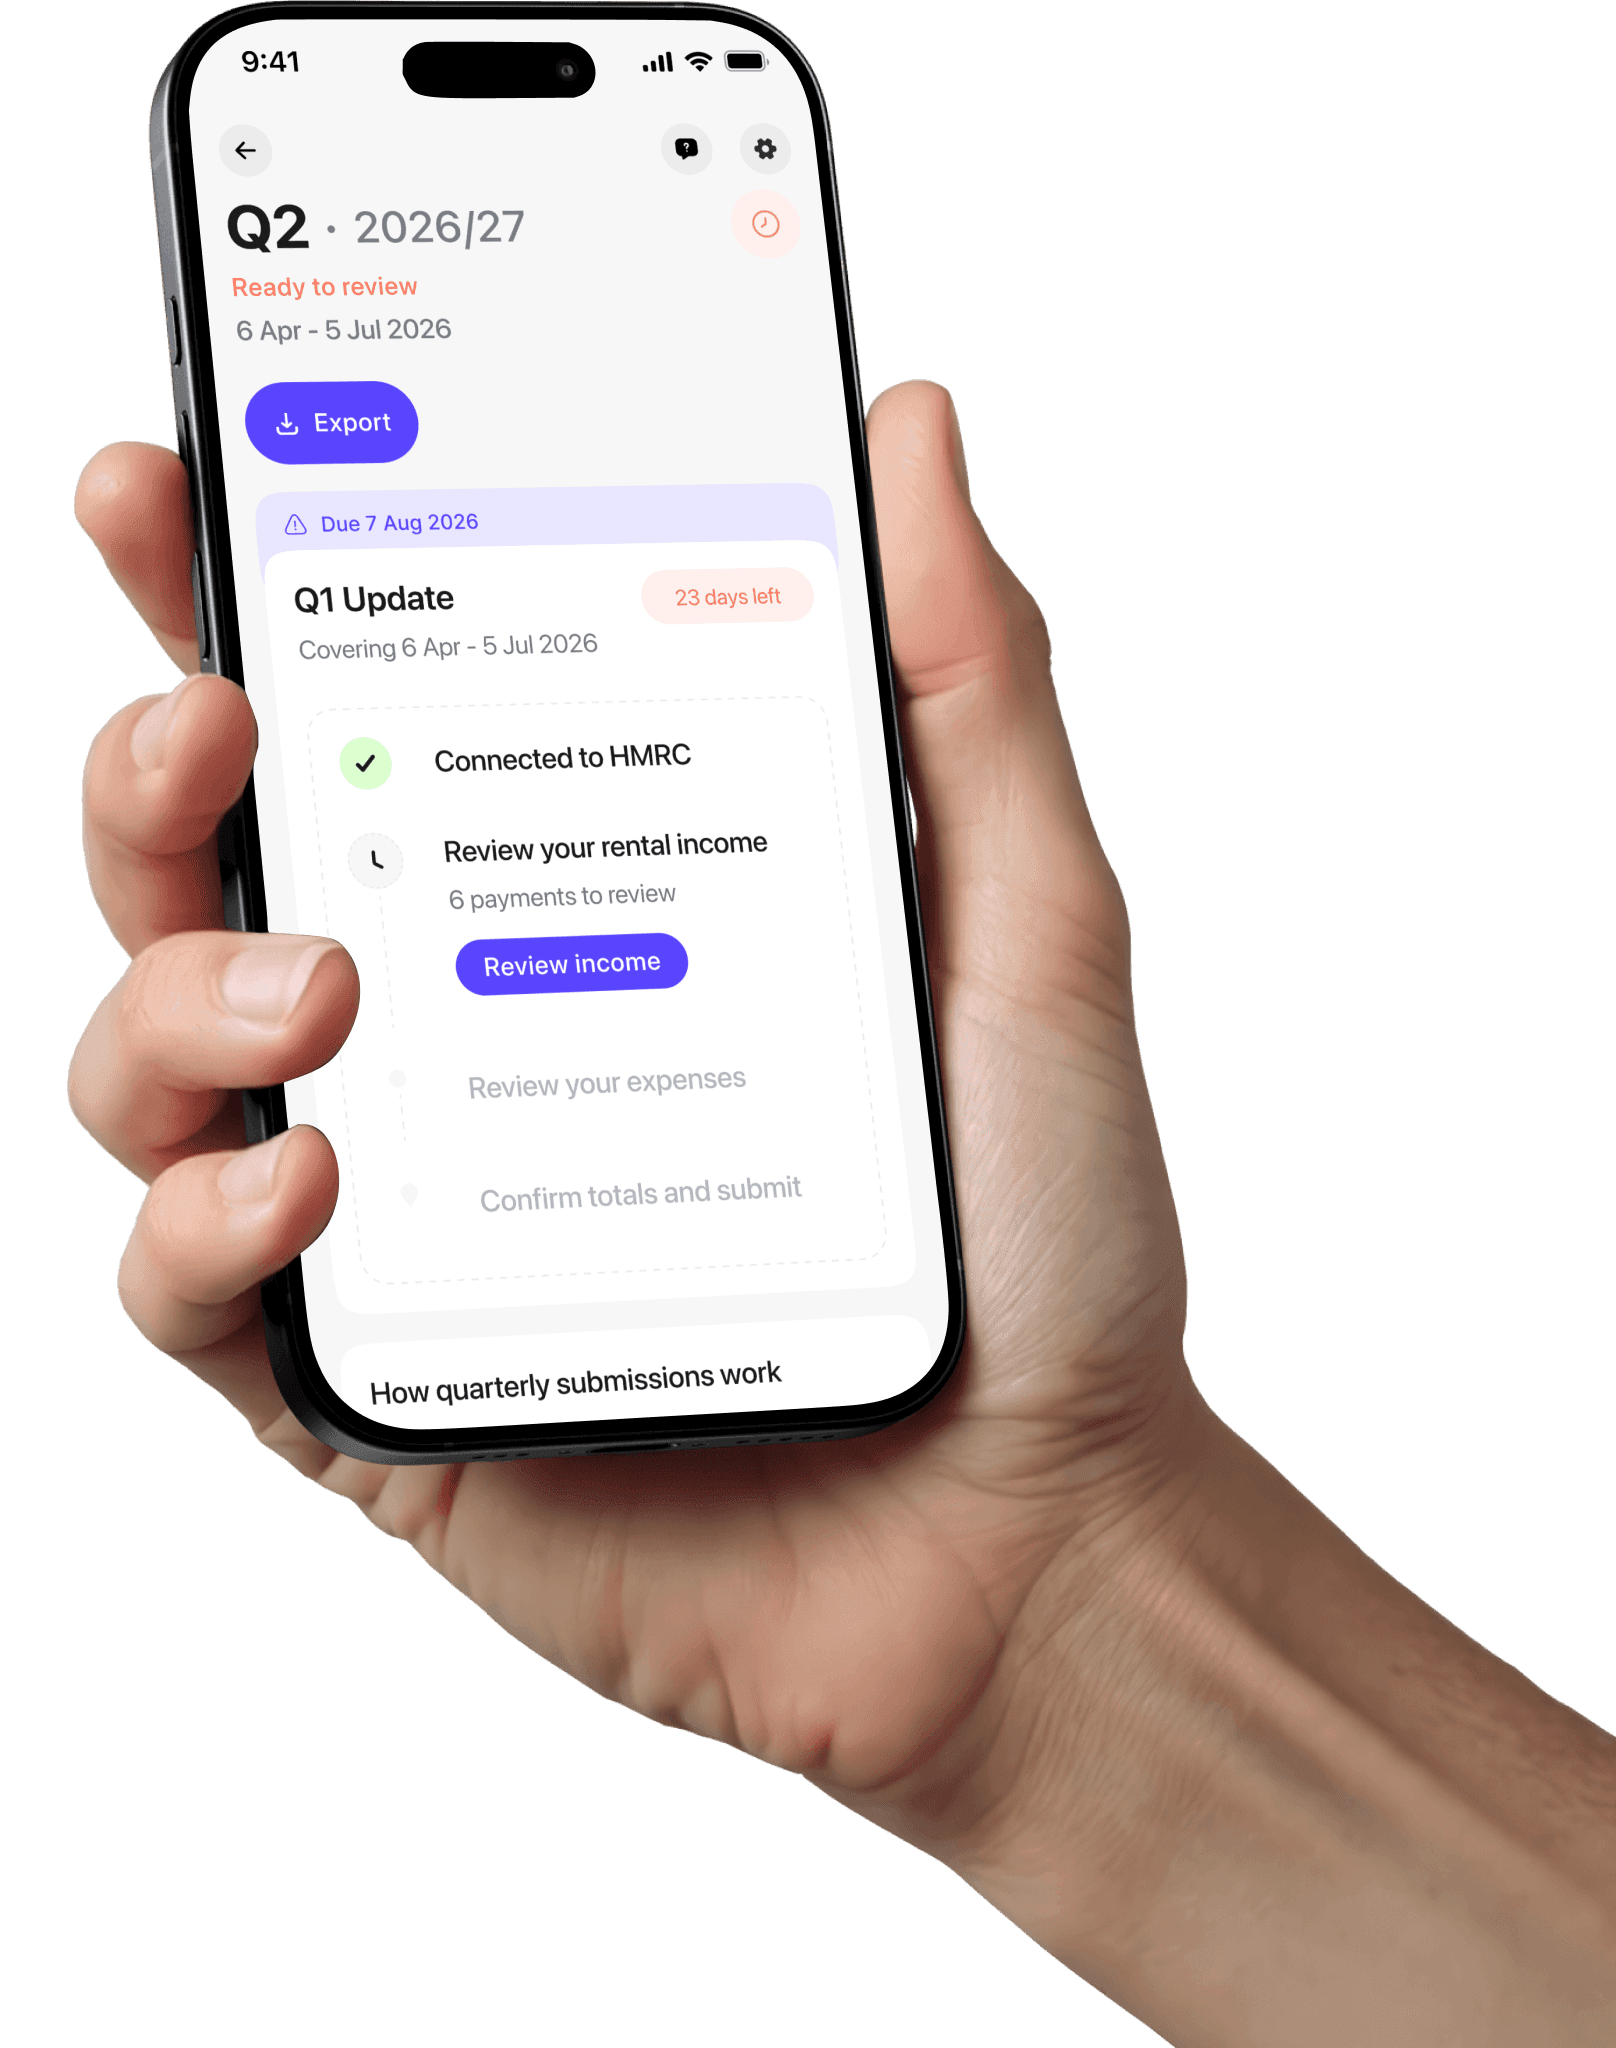
Landlord insurance premiums are an allowable expense against rental income under HMRC rules, provided the policy relates to the letting business. Buildings, contents, liability, legal expenses, and rent guarantee premiums can all be claimed in full in the tax year they are paid, and landlords can record and categorise them alongside other costs using August's expenses tracking feature.
For a detailed guide to choosing and comparing policies, including what to check at renewal, see August's article on what landlord insurance you need. Rent guarantee eligibility, including the referencing requirements, is covered in the complete guide to rent guarantee insurance.
Frequently asked questions
Does standard home insurance cover a rented property?
No. Standard home insurance assumes the policyholder lives in the property. Most policies exclude the rental scenario or allow the insurer to decline claims or void the policy if letting was not disclosed. Landlords must tell their insurer before letting and, in most cases, switch to a specialist landlord policy.
Do I need landlord insurance if I own the property outright?
Legally, no. With no lender requiring buildings cover, an unmortgaged landlord can let uninsured. In practice the exposure is identical: a liability claim, a fire, or a long uninhabitable period falls entirely on the landlord personally, which is why almost all unmortgaged landlords still insure.
What is the difference between loss of rent and rent guarantee insurance?
Loss of rent pays out when the property cannot be let because an insured event has made it uninhabitable. Rent guarantee pays out when the tenant stops paying, regardless of the property's condition. They address different risks and are often sold separately, though some comprehensive policies bundle both.
Is landlord buildings insurance calculated on market value or rebuild cost?
Rebuild cost: the amount it would cost to demolish and rebuild the property, which is usually lower than market value but can be significantly higher for listed buildings or unusual construction. Insuring at market value risks over-paying or having a claim adjusted on average.
Can I claim landlord insurance premiums as a tax expense?
Yes. Buildings, contents, liability, legal expenses, and rent guarantee premiums are all allowable against rental income under HMRC rules, deducted in the tax year the premium is paid.