Landlord accounting
Landlord accounting is the record-keeping and tax reporting required of anyone running a UK property business: recording rental income, recording allowable expenses, working out rental profit, and reporting the result to HMRC. HMRC's guidance on working out your rental income sets out what must be recorded. Since 6 April 2026, landlords above the Making Tax Digital threshold must keep those records digitally and report quarterly rather than once a year.
What records landlords must keep
HMRC requires records of all rental income received and all expenses incurred in connection with the letting. Income records should cover every rent payment, with the date, the amount and the property it relates to. Expense records need receipts, invoices or bank statements for every cost claimed: repairs and maintenance, landlord insurance, letting agent fees, safety certificate costs, accountancy fees, ground rent and service charges, and any other allowable expenses. Mortgage interest is recorded separately, because it is relieved through the Section 24 basic rate tax credit rather than deducted as an expense.
Records must be kept for at least five years after the 31 January filing deadline for the relevant tax year, and longer if HMRC opens an enquiry. Landlords within Making Tax Digital must keep those records digitally for the same period.
Cash basis and accrual basis
The cash basis is the default for unincorporated property businesses run by individuals or ordinary partnerships whose receipts for the tax year are £150,000 or less, under HMRC's Property Income Manual at PIM1092. Income is recognised when the money arrives and expenses when they are paid. A tenant who pays January's rent in February is treated as having paid in February. For most landlords this mirrors the bank statement and removes any need to track debtors and creditors.
The accrual basis recognises income when it is earned and expenses when they are incurred, whatever the cash does. It applies automatically once receipts exceed £150,000, and to companies, limited liability partnerships and trustees, none of which can use the cash basis. A landlord who is eligible for the cash basis but prefers accruals must elect for it on the return, and the election runs the other way round from the one traders make.
Landlords using August who are approaching £150,000 in receipts are the ones who most often get caught out here, because the threshold is tested on gross rent rather than profit and is applied separately to UK and overseas property businesses. Crossing it changes the basis for that year and triggers transitional adjustments.
Capital and revenue expenditure
A revenue expense is a repair that restores an item to its original condition, and it is deductible against rental income in the year it is paid. A capital expense is an improvement that takes the property beyond its original standard, and it is not deductible against rental income; it is added to the base cost and reduces any capital gain when the property is sold.
The line is not drawn by how modern the replacement is. Where an item is replaced with the nearest currently available equivalent, it stays a repair. HMRC's guidance at BIM46925 uses double glazing as its worked example: replacing single glazing with double glazing was once an improvement, but as double glazing became the industry norm it became simply a like-for-like replacement and an allowable revenue expense. Replacing a broken boiler with a modern equivalent works the same way. Going beyond the equivalent, by fitting triple glazing or enlarging the openings, moves part of the cost into capital and the expenditure is apportioned. The boundary is set out in more detail in our entry on capital improvements.
One point catches landlords out repeatedly. Capital allowances are not available on plant and machinery inside a residential dwelling-house, because section 35 of the Capital Allowances Act 2001 excludes it. Fitted kitchens, bathrooms, boilers and white goods in an ordinary buy-to-let all fall within that exclusion. For moveable items such as beds, sofas, carpets and appliances, the relief is replacement of domestic items relief, which covers like-for-like replacement but not the initial purchase.
Self Assessment for landlords
Landlords whose gross rental income exceeds £1,000 in a tax year must register for Self Assessment and file a return, unless the £1,000 property allowance covers it. The SA105 form is the supplementary page for UK property income, capturing gross rent, allowable expenses, rental profit or loss, and the mortgage interest figure that drives the Section 24 credit. Filing and payment are due by 31 January following the end of the tax year. A rental loss is carried forward and set against future property profits, and a return is still required in a loss-making year.
From working with self-managing landlords across the UK, the most consistent problem we see at Self Assessment time is missing receipts, not missing income. Most landlords report what they received accurately. It is the expense side, particularly cash payments, small maintenance jobs and mileage to and from properties, that is under-evidenced and therefore under-claimed. Keeping records through the year rather than reconstructing them in January makes a material difference to the bill.
Making Tax Digital for landlords
Making Tax Digital for Income Tax has applied since 6 April 2026 to landlords whose qualifying income exceeded £50,000 in 2024–25. The £50,000 test is applied to qualifying income, which is gross income from property and self-employment combined, taken from the previous year's return rather than from profit. The threshold falls to £30,000 from April 2027 and £20,000 from April 2028. Landlords who hold property through a limited company are outside the regime and continue to file corporation tax returns.
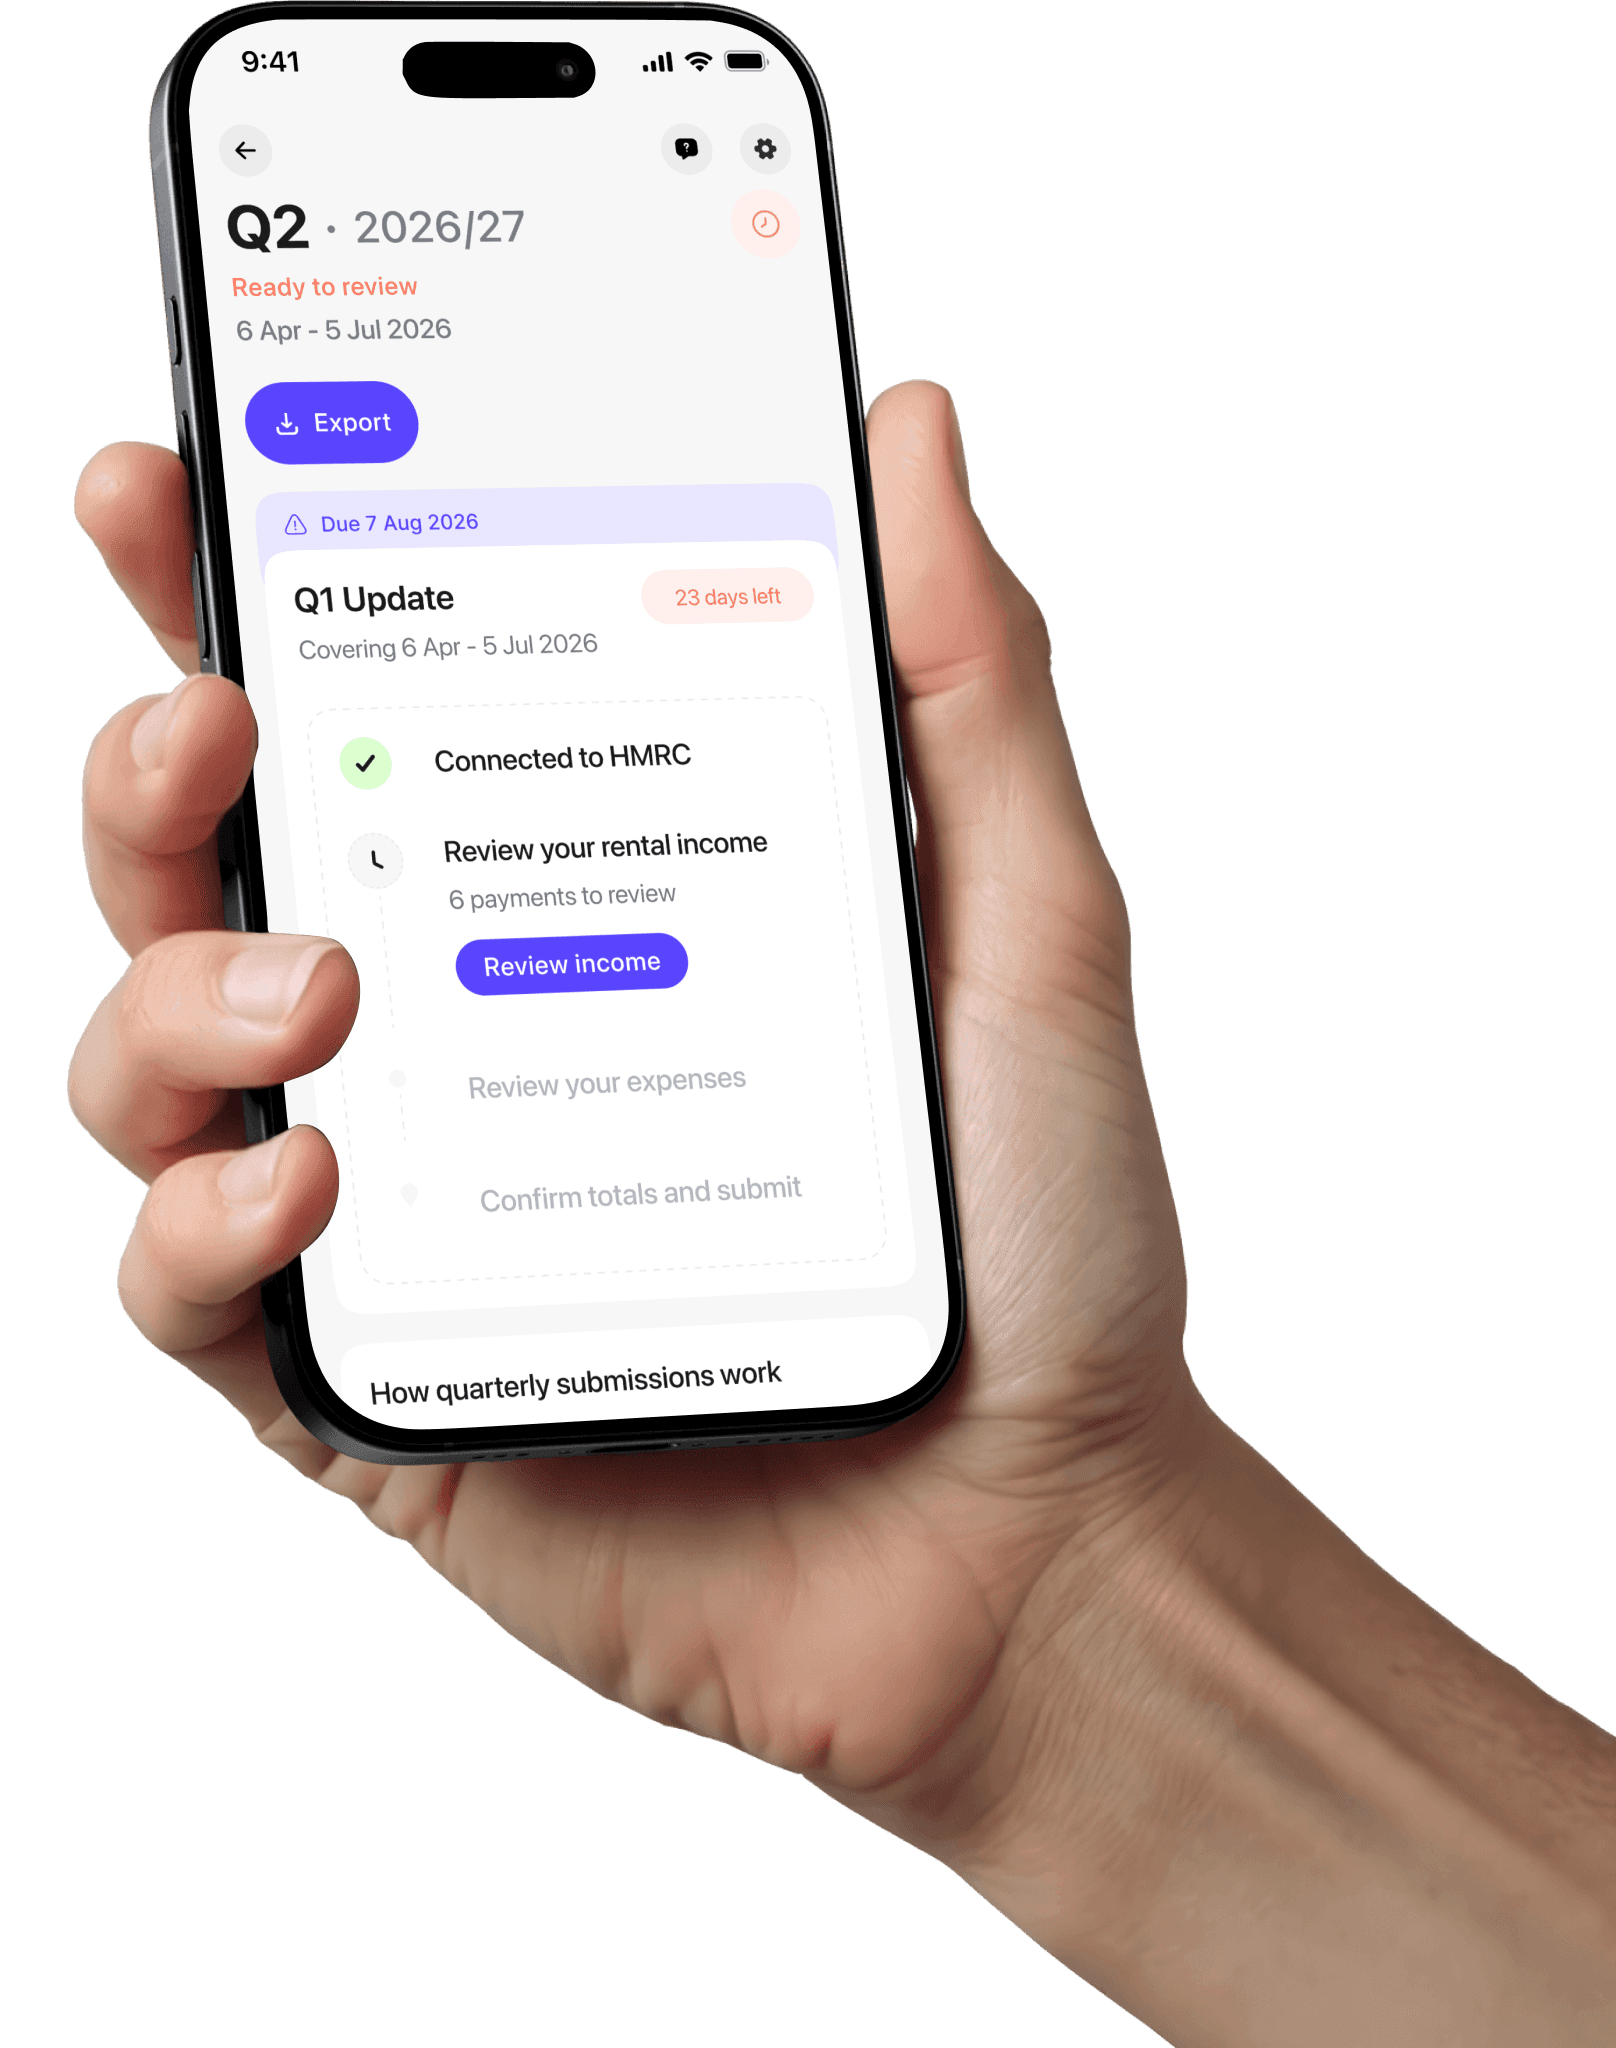
Those in scope keep digital records and send four quarterly updates through HMRC-recognised software, due on 7 August, 7 November, 7 February and 7 May. The updates are cumulative from 6 April rather than discrete three-month snapshots, so a correction in one quarter is carried into the next rather than resubmitted, and a quarter with no activity still needs a nil update. HMRC is not issuing penalty points for late quarterly updates during 2026–27, but that soft landing does not extend to late payment, to interest, or to a late annual return. Note the sequencing in the first year: a landlord mandated from April 2026 still files a conventional Self Assessment return for 2025–26 by 31 January 2027, and the first Final Declaration, for 2026–27, is due by 31 January 2028.
Making Tax Digital does not change how tax is calculated. It changes how records are kept and how often they are reported. August is recognised by HMRC for Making Tax Digital for Income Tax, and its MTD software for landlordskeeps the digital records, categorises expenses and files the quarterly update in one place.
Keeping the records
August's expenses tracking categorises costs against HMRC's property income categories and reconciles them against the bank feed, so the records behind the return are the same records used to run the portfolio. Choosing between a spreadsheet, a dedicated landlord tool and a general accountancy package is a separate decision, covered in our comparison of landlord accounting software. For what qualifies as an allowable expense and how to categorise it, see our guide to rental property expense categorisation.
Frequently asked questions
Do I need an accountant as a landlord?
There is no legal requirement. Many landlords with straightforward single-let portfolios file their own returns competently using software. An accountant earns their fee as complexity rises: multiple properties, mixed residential and commercial lets, a company structure, or a first year inside Making Tax Digital. Accountancy fees are themselves an allowable expense against rental income.
Do landlords use cash or accrual accounting?
Cash basis is the default for unincorporated landlords with receipts of £150,000 or less in the tax year. Income counts when received and expenses when paid. Above £150,000, and for companies, LLPs and trustees, the accrual basis is compulsory. An eligible landlord who prefers accruals must elect for it on the Self Assessment return.
Is replacing single glazing with double glazing a repair or an improvement?
A repair, in almost all cases. HMRC's position at BIM46925 is that double glazing became the industry standard, so fitting it in place of single glazing is now replacing like with currently available like rather than improving the property. The cost is deductible against rental income in the year it is paid. Upgrading beyond the modern equivalent, or enlarging the openings, moves part of the cost into capital.
Can landlords claim capital allowances?
Not on items inside an ordinary residential let. Section 35 of the Capital Allowances Act 2001 excludes plant and machinery for use in a dwelling-house, which covers fitted kitchens, bathrooms, boilers and white goods. Replacement of domestic items relief applies instead to like-for-like replacement of moveable items such as beds, sofas, carpets and appliances. Capital allowances remain available on qualifying plant in commercial property and in the common parts of a building containing two or more separate dwellings.
When must landlords use Making Tax Digital?
From 6 April 2026 for landlords with qualifying income above £50,000 in 2024–25, from April 2027 above £30,000, and from April 2028 above £20,000. Qualifying income is gross property and self-employment income combined, not profit. Company landlords are outside the regime. Those in scope keep digital records and submit four cumulative quarterly updates a year through recognised software, followed by a Final Declaration by 31 January.