Tax & Accountancy
UK-wide
Allowable expenses for landlords: what you can claim in 2026/27

Allowable expenses for landlords are the running costs of a letting business that HMRC lets you deduct from rent before it works out your taxable profit. A cost qualifies when you incur it wholly and exclusively for the letting and it is revenue rather than capital in nature. Repairs, agent fees, insurance, ground rent and service charges, accountancy fees, bills you pay for tenants and business travel all qualify. Mortgage interest does not: it earns a separate 20% tax credit, which rises to 22% from 6 April 2027. The rules in this guide are correct as at 24 October 2026.
What expenses can I claim as a landlord?
Landlords can claim these costs against rental income in the 2026/27 tax year, provided each one passes the test in the next section:
Repairs and maintenance that restore the property
Letting agent and property management fees
Landlord insurance premiums
Ground rent and service charges on leasehold property
Utility bills and council tax you pay for the letting
Accountancy and legal fees for the letting business
Advertising and tenant-finding costs
Travel for the letting business, including the mileage rate
Replacing furniture, appliances and furnishings like for like
Phone, stationery and other administration costs
Services you pay for, such as cleaning, gardening and pest control
Revenue costs you incurred up to seven years before your first letting
Mortgage interest and other finance costs sit outside this list because HMRC relieves them through a tax credit instead of a deduction. For how these deductions fit into your overall bill, see our guide to how rental income is taxed.
The test every expense must pass
An expense is allowable only if you incur it wholly and exclusively for the letting business and it is a revenue cost, not a capital one. HMRC applies both tests to every claim, as its guidance on working out your rental income sets out.
Wholly and exclusively means the cost serves the letting and nothing else. Where a cost is partly personal, such as a phone contract or a car, you can claim only the business share, and only if you can identify and measure it.
Revenue costs keep the property running in its existing condition, and are known as revenue expenses. Capital costs buy, improve or extend the property. A repair restores something to its original condition and is allowable; capital improvements, such as an extension or a loft conversion, are not. HMRC treats an upgrade as a repair when the improvement is incidental, for example replacing single glazing with modern double glazing.
The full list of allowable landlord expenses
1. Repairs and maintenance
Repairs and maintenance are fully deductible in the year you pay for them. Typical allowable work includes replacing a boiler with a broadly equivalent model, fixing a leaking roof, repointing brickwork, mending windows, doors, gutters and pipes, redecorating between tenancies, and treating damp or pests. Replacing a basic kitchen with a high-specification one is an improvement, so only the cost of a like-for-like replacement would count.
2. Letting agent and management fees
Fees you pay a letting agent are fully deductible, including tenant-find fees, monthly management fees, renewal fees and charges for arranging repairs. Management fees typically run at 8% to 15% of the monthly rent.
3. Landlord insurance
Premiums for insurance that covers the let property are allowable. That includes buildings and contents cover for a furnished let, landlord liability cover, rent guarantee insurance and legal expenses cover. A home insurance policy on a property you live in does not qualify.
4. Ground rent and service charges
Leasehold landlords can deduct ground rent and service charges paid to the freeholder or managing agent. Where part of a service charge goes into a sinking fund, that part becomes deductible only when the fund is spent on repairs, not when you pay it in.
5. Utility bills and council tax
Utility bills, water rates and council tax are deductible when you pay them for the letting, for example when bills are included in the rent or during an empty period between tenants. If you also live in the property for part of the year, claim only the share that relates to the letting.
6. Accountancy and legal fees
Accountancy fees for preparing your rental accounts and tax return are allowable. So are legal fees for a let of a year or less, for renewing a lease of under 50 years, for drawing up tenancy agreements and for evicting a tenant. Legal and survey fees for buying a property or arranging a new mortgage are capital costs and are not allowable against rent.
7. Advertising and tenant-finding costs
The cost of finding tenants is deductible, including listing fees on property portals, photography and floor plans, and referencing charges you pay yourself.
8. Travel for the letting business
Journeys you make wholly for the letting business are allowable, such as inspections, meeting contractors or handing over keys. You can claim either the business share of your actual vehicle costs or HMRC's mileage rate, which rose to 55p per mile for the first 10,000 miles from 6 April 2026, with 25p per mile after that. Our mileage expense calculator maps each journey and applies both rates. Keep a log of dates, destinations and the reason for each trip.
9. Replacing furniture, appliances and furnishings
Replacement of domestic items relief lets you deduct the cost of replacing furniture, furnishings, appliances and kitchenware in a let dwelling, under section 311A of the Income Tax (Trading and Other Income) Act 2005. The relief covers a like-for-like or modern equivalent replacement, plus disposal costs, less anything you receive for the old item. It does not cover the first purchase of an item, and if you upgrade, only the cost of an equivalent item counts. The relief does not apply if you let a room in your own home.
10. Phone, stationery and administration
Phone calls, postage, stationery and software you use for the letting are allowable. Where a phone or broadband contract is shared with personal use, claim the business share on a reasonable basis.
11. Services you pay for
Costs of services the tenancy includes, such as cleaning, gardening, window cleaning and pest control, are deductible when you pay for them.
12. Costs before your first letting
Revenue costs you incur in the seven years before your letting business starts are deductible, as covered in the section on pre-letting costs below.
Mortgage interest and finance costs
Individual landlords cannot deduct mortgage interest from rental income; they receive a tax credit instead. The restriction applies to residential lets and has been fully in force since 6 April 2020, under section 272A of the Income Tax (Trading and Other Income) Act 2005, the rule landlords know as Section 24.
For the 2026/27 tax year the credit is 20% of your finance costs, which include mortgage interest, interest on loans to buy furnishings and arrangement fees. From 6 April 2027, section 7 of the Finance Act 2026 introduces separate property income rates of 22%, 42% and 47%, and HMRC's technical note confirms the finance cost credit rises to 22% at the same time. A landlord with £10,000 of mortgage interest would receive a £2,000 credit in 2026/27 and a £2,200 credit in 2027/28, against a higher tax rate on the profit itself.
Companies are not restricted and deduct interest in full. Our rental income tax calculator applies the credit to your figures.
What landlords cannot claim
Non-allowable expenses are costs that fail either the wholly and exclusively test or the revenue test. The main ones are:
Capital improvements, such as extensions, loft conversions and upgraded kitchens or bathrooms.
Purchase costs, including Stamp Duty Land Tax, conveyancing and survey fees when you buy.
Mortgage capital repayments, at any time and in any ownership structure.
The first purchase of furniture and appliances, since only replacements qualify.
Personal costs, unless you can identify and measure the business share.
Your own time, since you cannot pay yourself a deductible wage for managing your own lets.
Fines and penalties, which HMRC never allows.
Capital spending is not wasted for tax purposes. Many capital costs reduce your Capital Gains Tax when you sell, and some equipment qualifies for capital allowances, although these rarely apply to the fabric of a residential let. Keep every capital invoice for the sale calculation.
Expenses before your first tenancy
Pre-letting costs are one of the most overlooked deductions for new landlords. Revenue costs you incur in the seven years before your letting business starts are allowable if they would have been deductible once the business was running, under the rule HMRC explains at PIM2505. HMRC treats them as incurred on the day the letting starts.
Qualifying examples include advertising for your first tenant, a gas safety check and an energy performance certificate. Work that brings a newly bought, run-down property up to a lettable standard is usually capital, so it does not qualify.
The £1,000 property allowance or actual expenses
If your gross property income is £1,000 or less in a tax year, you do not need to report it. If it is more, you can deduct either a flat £1,000 property allowance or your actual allowable expenses, but not both. Most landlords with a mortgage, agent fees or repairs save more by claiming actual expenses.
Cash basis or traditional accounting
The cash basis is the default for most individual landlords whose rental receipts are £150,000 or less a year, according to HMRC's Property Income Manual, and has been since the 2017/18 tax year. Under the cash basis you record rent when it arrives and expenses when you pay them. Traditional accounting matches income and costs to the period they relate to, which can suit a landlord with large bills straddling the year end. To use it, you elect on your return.
How to claim landlord expenses on your tax return
Landlords claim allowable expenses on the UK property pages (SA105) of their Self Assessment return. The form has separate boxes for repairs and maintenance, legal and professional fees, costs of services and other expenses, so it helps to categorise each cost as you pay it. Finance costs go in their own box and produce the credit rather than a deduction.
The tax year runs from 6 April to 5 April. The online return and any tax due are both due by 31 January after the end of the tax year.
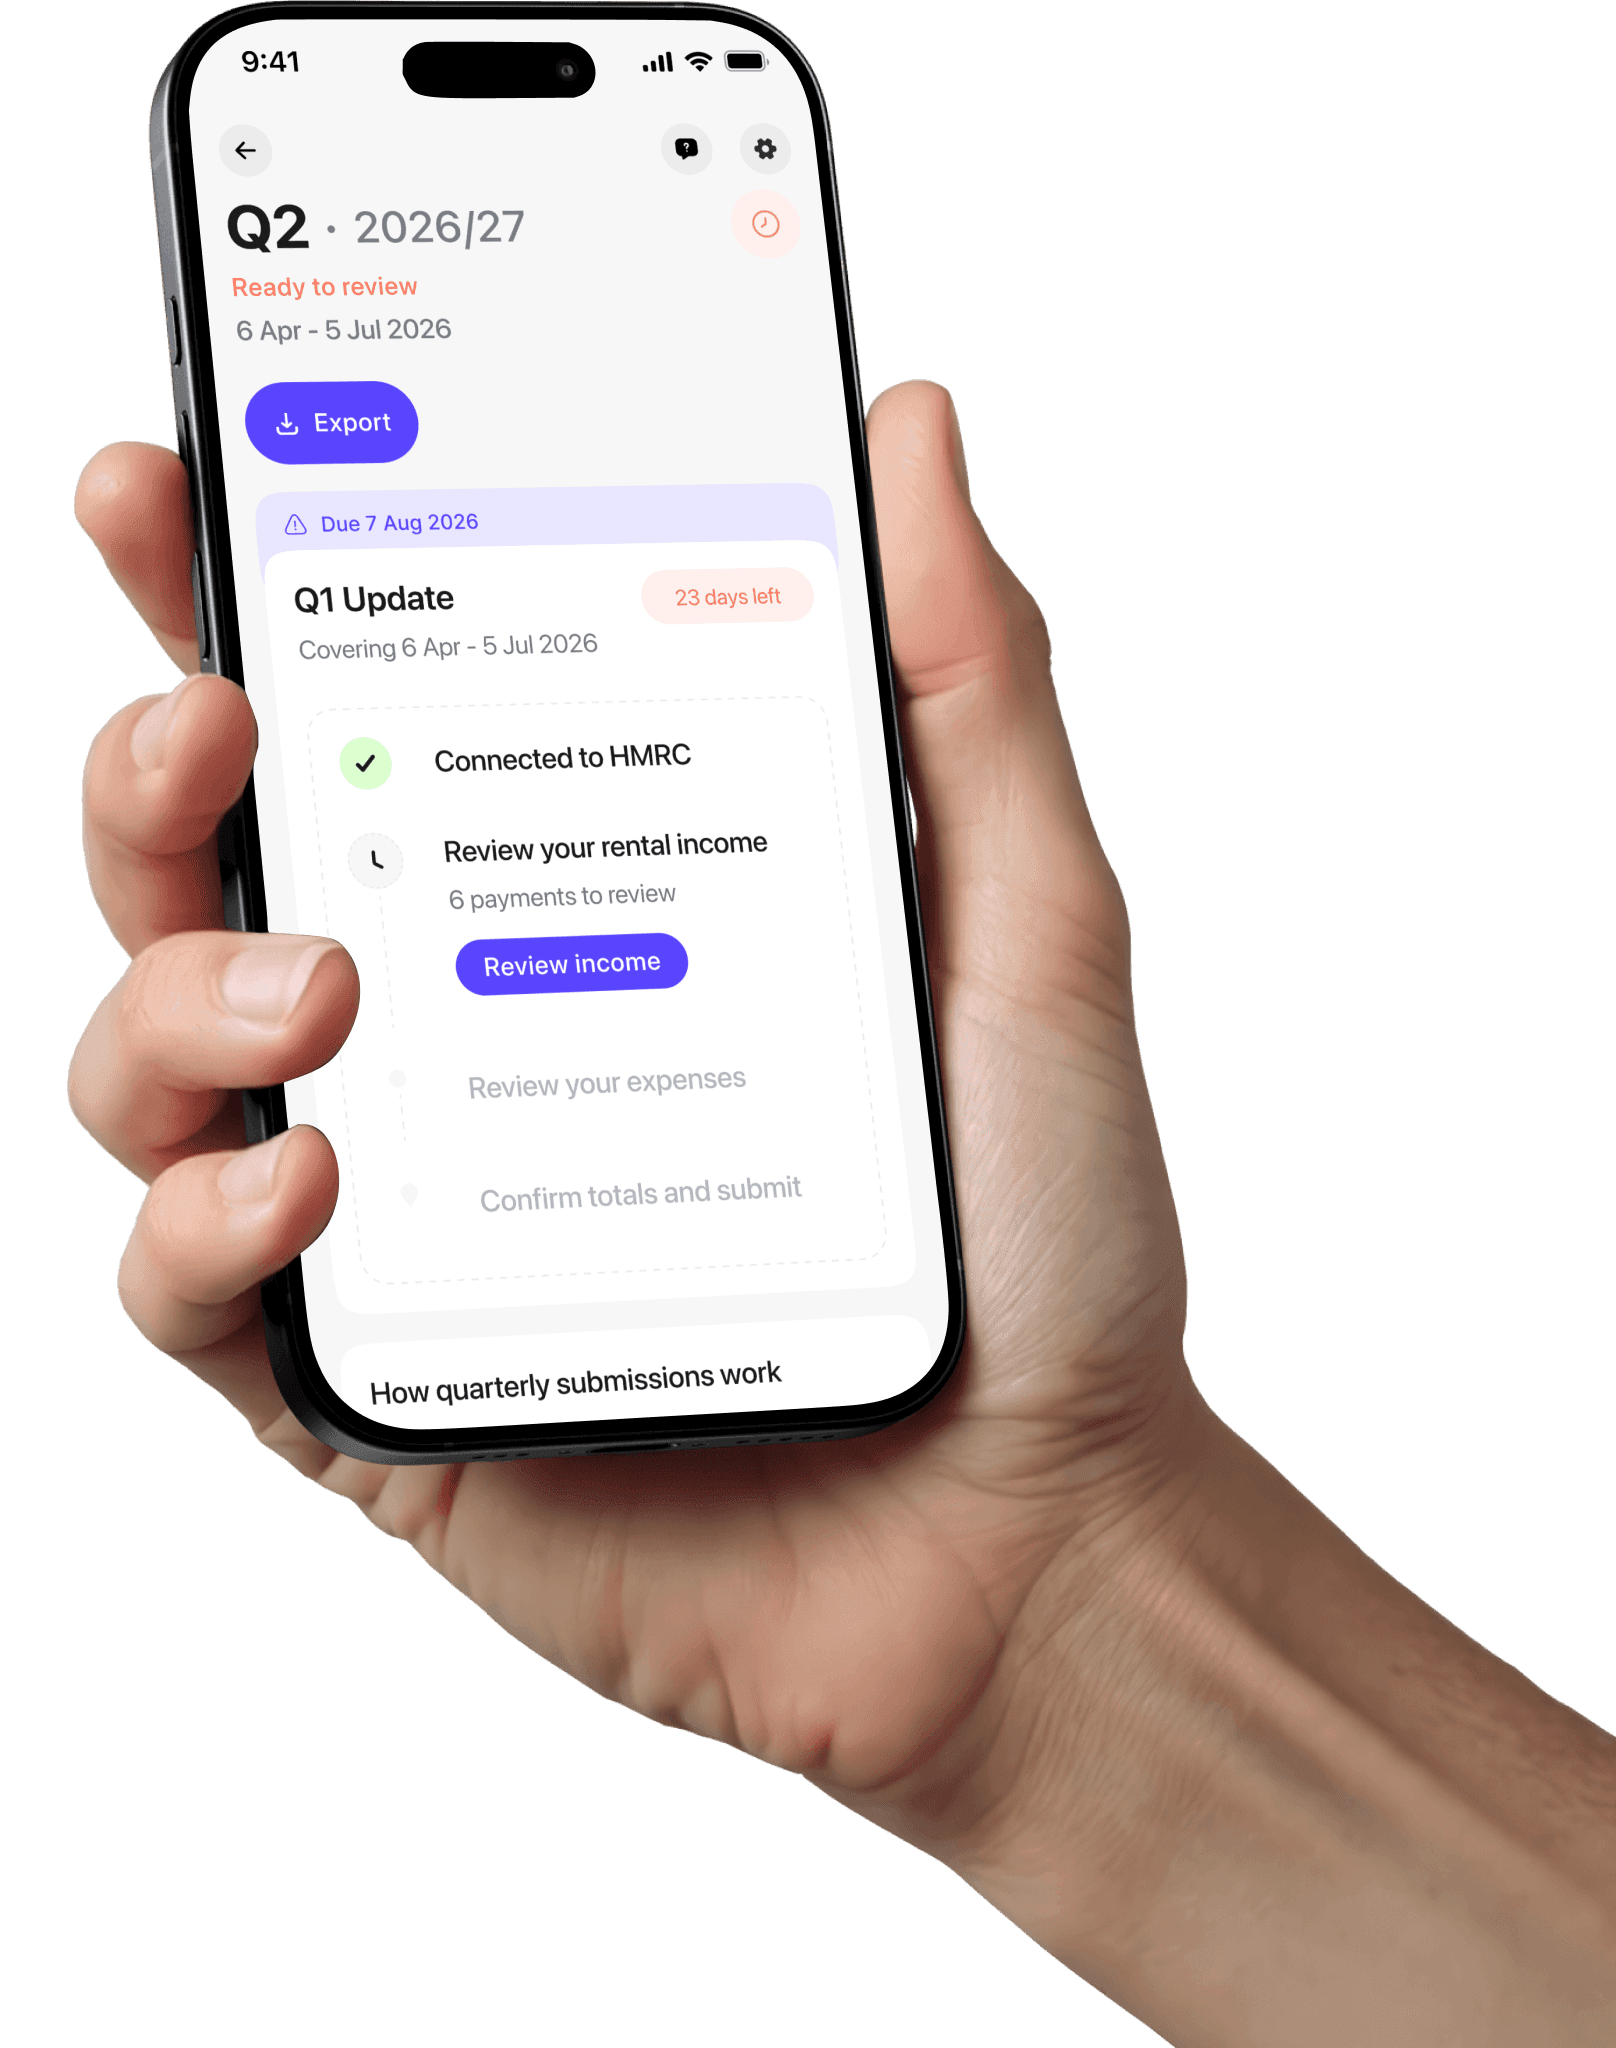
Making Tax Digital for Income Tax changes the timetable for larger landlords. Since 6 April 2026, landlords and sole traders with qualifying income over £50,000 must keep digital records and send HMRC quarterly updates, with the threshold falling to £30,000 from April 2027 and £20,000 from April 2028. Our guide explains how quarterly updates work, and August is software HMRC recognises for Making Tax Digital.
If you have several properties, overseas lets or joint ownership, an accountant who specialises in property will usually save more than their fee, and the fee itself is allowable.
Keeping records of landlord rental income and expenses
The expenses you can claim are only as good as the records behind them. HMRC expects you to keep receipts, invoices, bank statements, mileage logs and tenancy agreements for at least five years after the 31 January filing deadline for the tax year.
In our work with self-managing landlords, the expenses that go unclaimed are rarely the large ones. They are the small, recurring costs, such as certificate renewals, portal listings and short trips to a property, that never make it from a bank statement into the return. A landlord spreadsheet works if you update it every month. August's expense tracking records each cost against the right property and category as you pay it, so the year-end figures already exist.
Allowable expenses for HMOs and multi-let properties
HMO landlords claim under the same rules, but their list of deductible costs is longer. Typical extras include HMO licence fees, cleaning and lighting for communal areas, broadband and utilities included in the rent, and fire alarm, emergency lighting and fire door maintenance.
Landlords running HMOs on August are the group most likely to miss communal running costs, because those bills arrive in the landlord's own name and look like household spending. Tagging them to the property when they arrive closes that gap.
Do the rules differ in Scotland, Wales or Northern Ireland?
The rules on what counts as an allowable expense are the same across the UK, because they come from UK income tax law. What differs is the rate of tax on the profit. Scottish taxpayers pay Scottish income tax rates, and the new property rates from April 2027 apply in England, Wales and Northern Ireland, with the UK Government working with the Scottish and Welsh Governments on their own property rates.
Frequently asked questions
Can I claim for a new boiler?
Usually, yes. Replacing a boiler that has failed or is beyond economic repair with a broadly equivalent modern model counts as a repair. Installing heating where there was none, or a major upgrade to the system, is capital expenditure. The line is fact-specific, so check large or unusual jobs with your accountant.
Are costs during an empty period between tenants deductible?
Yes, if the property is genuinely available to let and you are actively looking for a tenant. Insurance, utilities, council tax and repairs during that period are allowable. If the property is empty because you are renovating it or using it yourself, HMRC may refuse the costs.
Can I claim for running my lets from home?
You can claim a reasonable share of household costs, such as heating, lighting and broadband, for the time and space you use only for the letting business. Apportion actual bills by floor area and hours of use and keep a note of your method. The amounts are usually small.
Do the same rules apply if I own property through a limited company?
The expense rules are broadly the same, but a company pays Corporation Tax and deducts mortgage interest in full rather than receiving a credit. If you are weighing up holding property in a limited company, factor in the costs of running a company and of moving existing properties into one.
Claim everything you are entitled to
Every allowable expense rests on three things: the cost is for the letting alone, it maintains rather than improves the property, and you can prove you paid it. Apply those tests as you go and the return takes care of itself. You can start tracking your expenses free for up to two properties.
This article is general information, not tax advice. Tax rules change and individual circumstances vary; the rules above are correct as at 24 October 2026. Take independent advice before acting.

Author
August Team
The August editorial team lives and breathes rental property. They work closely with a panel of experienced landlords and industry partners across the UK, turning real-world portfolio and tenancy experience into clear, practical guidance for landlords.