Property Finance & Investment
How to build a property portfolio in the UK

Building a property portfolio in the UK means buying a first rental property on sound numbers, running it well, then using its rental surplus and rising equity to fund the next purchase, and repeating the cycle. Most landlords grow one or two properties at a time, and the constraints change as they go. Early on, the limit is the deposit. From the fourth mortgaged property, lenders assess the whole portfolio. Beyond that, the limit is the time it takes to manage everything well. This guide covers each stage, with costs and tax rules checked in October 2026.
Is building a property portfolio worth it?
A property portfolio can still produce rental income and long-term capital growth, but the margins are thinner than they were a decade ago.
Higher mortgage rates and tighter tax rules on individual landlords both cut into returns. On the other side, rents and demand for rented homes remain strong. Whether it works for you depends on your tax position, how much you borrow and how much time you can give it. Our analysis of whether being a landlord is still worth it sets out the numbers in detail.
How much money do you need to start a property portfolio?
Most landlords need around a third of the purchase price in cash to buy their first buy-to-let, because lenders typically lend up to 75% and the stamp duty surcharge applies on top. For a £200,000 property in England:
Cost | Amount |
|---|---|
Deposit at 25% | £50,000 |
Stamp Duty Land Tax including the 5% surcharge on additional homes | £11,500 |
Legal, survey, lender and broker fees (typical estimate) | £3,000 to £5,000 |
Cash needed before any reserve | £64,500 to £66,500 |
The surcharge has been 5 percentage points on top of standard rates since 31 October 2024, under HMRC’s rules for buying an additional residential property. Scotland and Wales use their own land taxes. Check your figure with the stamp duty calculator.
Keep a cash reserve as well. Three to six months of mortgage payments and running costs covers a void period or a boiler replacement without forcing a sale.
How to start a property portfolio
Starting a portfolio takes five steps:
Set a goal and a buying rule
Decide how you will own the properties
Buy the first property on the numbers
Borrow in a way that leaves room for the next purchase
Run the first property as a business from day one
If you have not yet bought a rental property, our beginner’s guide to investing in UK property covers the basics first.
1. Set a goal and a buying rule
A portfolio grows faster when every purchase meets the same written rule. Decide whether you are buying for monthly income, long-term growth or a balance of both. Then turn that into a test each property must pass, such as a minimum net yield, a maximum price or a target area. The property investment strategies you choose, whether single lets, HMOs or refurbishments, follow from that goal.
2. Decide how you will own the properties
Choose your ownership structure before the first purchase, because changing it later is expensive. Individuals pay income tax on rental profit and get only basic-rate relief on mortgage interest. Companies pay Corporation Tax and deduct interest in full. Moving properties into a company later can trigger stamp duty and Capital Gains Tax. Our guide to whether a limited company is right for you explains the trade-off. Take advice from an accountant who works with landlords before you decide.
3. Buy the first property on the numbers
A first property should pay its way after every cost, not just at the advertised gross yield. Allow for:
mortgage interest at a realistic rate
insurance and repairs
compliance certificates
voids
letting fees if you use an agent
Run each deal through the buy-to-let investment calculator before you offer. A property that only works on optimistic rent will slow every purchase that follows.
4. Borrow in a way that leaves room for the next purchase
Borrowing choices on the first property set the pace for the second. Interest-only mortgages keep monthly costs low and leave more surplus to save towards the next deposit, at the cost of repaying the full loan at the end. Lenders test rent against a stressed interest rate, so a property with strong rental cover also helps later applications. Keep borrowing comfortable rather than maximised.
5. Run the first property as a business from day one
Clean records from the first tenancy make every later mortgage application easier. Keep rent, costs and certificates separate for each property, and keep the compliance basics up to date, from gas safety to the Renters’ Rights Act duties that apply to every tenancy. Landlords using August are often surprised the first time they see costs broken down by property, because one property is quietly eating the profit of another. Tracking income and expenses per property shows that early, while it is still cheap to fix.
How to grow a property portfolio
Growing a property portfolio depends on four things:
funding each new deposit
planning ahead for the fourth mortgaged property
keeping management under control
reviewing which properties earn their place
Recycle equity to fund the next deposit
Most portfolios grow by remortgaging properties that have risen in value and using the released cash as the next deposit.
Here is an example. A landlord buys at £200,000 with a £150,000 mortgage. Some years later the property is worth £240,000. At 75% loan to value they can borrow £180,000, releasing about £30,000 before fees. The rent must still cover the larger loan at the lender’s stressed rate, so remortgaging works only on properties with good rental cover.
Some investors speed this up with the BRRRR method: they buy below value, refurbish, then refinance at the new valuation. Track each property’s current value with property insights so you know when one has enough equity to release.
Plan for your fourth mortgaged property
At four mortgaged buy-to-lets you become a portfolio landlord, and every new loan is assessed against your whole portfolio. Individual lenders also cap how many loans they will hold for you. Our guide to how many buy-to-let mortgages you can have sets out typical limits. Prepare for this before the fourth purchase. Lenders will ask for a schedule of every property, its value, its mortgage and its rent.
Keep management under control
Time, not finance, is what usually stops self-managing landlords. From supporting landlords as they move from three properties to five, we see the same pattern: tenant requests, renewals and certificates for every property land on the same person, and admin that took an evening a month turns into a second job.
Decide early which tasks you keep and which you hand to an agent. Make sure one system shows every property’s rent, compliance and documents. Software built for portfolio landlords does that without the cost of full management.
Review the portfolio and sell what holds it back
A growing portfolio needs an annual review, because one weak property can block finance on the rest. Compare each property’s net yield, equity and condition against your buying rule. Selling an underperformer can free capital for a better purchase. Our guide to selling a property portfolio covers the tax and timing.
Tax rules that shape portfolio growth
Tax treatment decides how much rental surplus is left to reinvest, and three rules matter most for individual landlords in England as at October 2026.
Mortgage interest relief. Individual landlords cannot deduct mortgage interest from rental profit. They receive a tax credit at the basic rate instead, which reduces after-tax returns most for higher-rate taxpayers with large mortgages.
Higher property income rates from 6 April 2027. The government will tax property income at separate rates of 22%, 42% and 47% in England and Northern Ireland, two points above the main income tax rates. The mortgage interest credit will rise to 22%, according to HM Treasury’s technical note published on 26 November 2025.
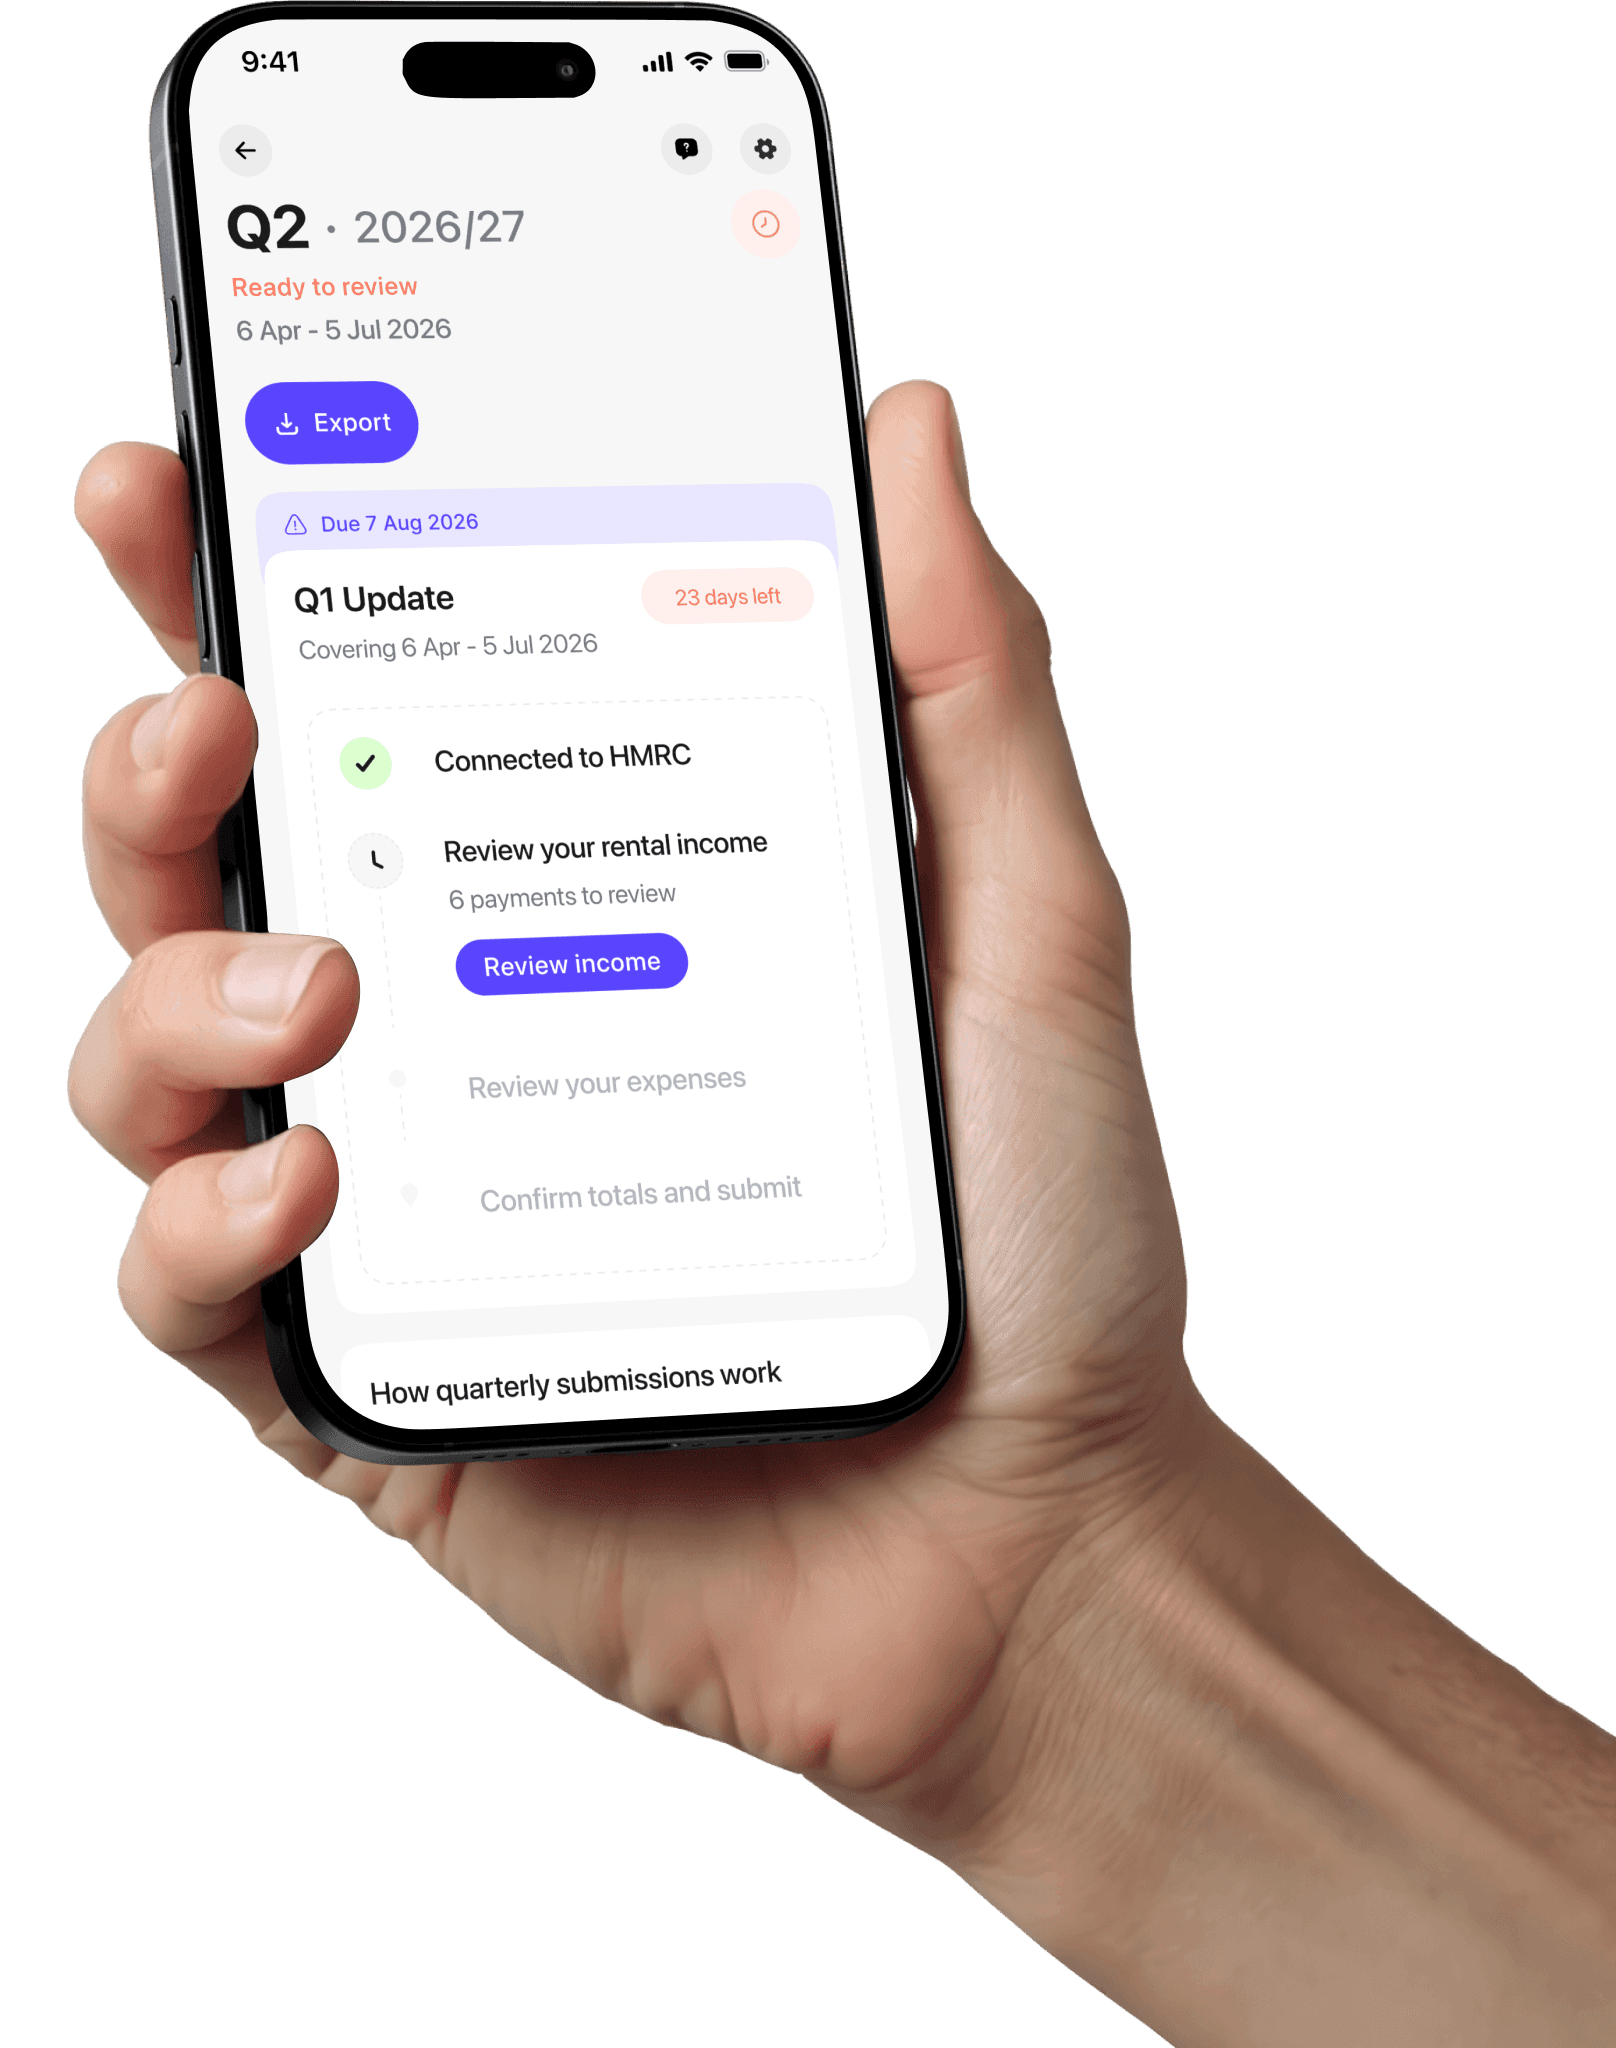
Making Tax Digital. Landlords with qualifying income over £50,000 have kept digital records and sent quarterly updates to HMRC since April 2026, and the threshold falls to £30,000 in April 2027. Our Making Tax Digital hubcovers what each landlord needs to do.
These rules are the main reason landlords building larger portfolios review their ownership structure as they grow.
Common mistakes when building a property portfolio
The mistakes that stall portfolios are usually financial rather than practical:
Too little reserve: borrowing to the limit on every purchase, which leaves nothing for voids or rate rises.
Bending the rule: buying outside your own buying rule because a deal feels urgent.
Unclear figures: mixing personal and property money, so the true return per property is unclear.
Late tax advice: leaving ownership decisions until after the third or fourth purchase.
Frequently asked questions
How long does it take to build a property portfolio?
It depends on how quickly you can fund deposits. Landlords who rely on savings and rental surplus often add a property every two to three years. Those who recycle equity or refurbish below-value properties can move faster but take on more risk.
Can you build a property portfolio from nothing?
Not with a buy-to-let mortgage, because lenders usually want a 25% deposit. Some people start with lower-capital strategies such as rent-to-rent or joint ventures, but each carries legal and financial risks to understand first.
What is the difference between a property portfolio and a portfolio landlord?
A property portfolio is simply the rental properties you own, of any size. Portfolio landlord is a lending term for anyone with four or more mortgaged buy-to-lets.
What is the best way to keep track of a growing portfolio?
Use one system that shows rent, costs, documents and compliance for every property, and keep it current from the first purchase. You can start using August for free and add properties as the portfolio grows.

Author
August Team
The August editorial team lives and breathes rental property. They work closely with a panel of experienced landlords and industry partners across the UK, turning real-world portfolio and tenancy experience into clear, practical guidance for landlords.